Neetu Yoshi Ltd Share Analysis
Neetu Yoshi Ltd, incorporated in January 2020, is a metallurgical based railway component manufacturer based in Dehradun, Uttarakhand. These components are critical in nature and are used in braking, suspension, coupling and propulsion systems across different parts of the railway ecosystem, including freight wagons, passenger coaches, locomotives and track infrastructure. Going forward, Neetu Yoshi Ltd is looking to move beyond individual components and expand into higher-value products such as complete bogie assemblies, couplers, track turnout fittings and springs. Neetu Yoshi Ltd is closely linked to the ongoing modernization of India’s railway infrastructure. Projects such as Vande Bharat trains, Dedicated Freight Corridors and broader railway capacity expansion could create additional demand for its products
Table T1
Neetu Yoshi Ltd offers the prospect of a high growth story within the Indian Railways ecosystem that is not yet well known within the broader investor community. With multiple levers of order book visibility, expansion into new products and commissioning of new facilities, Neet Yoshi Ltd may surprise on the upside on the growth front. At the same time, past promoter actions leave scope for doubt and will need to be assessed in a nuanced manner by investors looking to increase exposure to the Railways theme. The stock still trades on the BSE SME platform and carries significant liquidity risk, if the expected high growth does not materialize for whatever reason. Neetu Yoshi is one of the many SME stocks we have been tracking for a few months now where the growth outlook is not clouded by the geopolitical macro outlook plaguing India in 2026.
Neetu Yoshi Ltd Company Summary
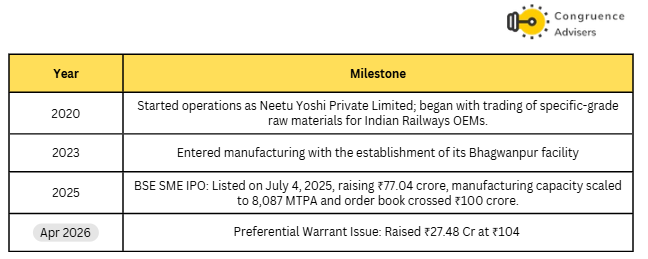
Neetu Yoshi started in 2020 with a simple business model. The promoters, Himanshu Lohia and Subodh Lohia, initially participated in Indian Railways’ scrap auctions and supplied specific-grade raw materials to railway component manufacturers. At this stage, the company did not have any manufacturing setup of its own. However, working closely with component manufacturers gave the promoters a good understanding of the railway value chain and the different components used across wagons, coaches and other railway applications.
As the promoters became more familiar with the industry, they saw that there was more value to be created by moving from trading into manufacturing. Neetu Yoshi Ltd set up a CNC machine shop in Rudrapur, Uttarakhand in 2022. It sourced castings from other component manufacturers, carried out the machining in-house and supplied the finished components back to the Indian Railways.
Moving to become Railway safety critical component manufacturer:
The Rudrapur experience gave Neetu Yoshi Ltd a better understanding of the products, customer requirements and margins across different components. With this experience, the promoters set up their own integrated foundry and machining facility at Bhagwanpur, Uttarakhand. The facility subsequently received Class “A” RDSO certification, allowing Neetu Yoshi Ltd to manufacture and supply critical -safety approved railway components.
Role of Himanshu’s father
Yogesh Lohia, Himanshu Lohia’s father, has been involved in guiding the promoters as they have built and expanded Neetu Yoshi Ltd. His prior experience in the foundry as he ran Jagadamba Liquified Steels earlier, a RDSO approved manufacturer of critical safety steel and iron casting, gives him familiarity with the manufacturing process and the railway ecosystem. His role appears to be more of a strategic and mentoring support, helping Himanshu and Subodh with industry knowledge, manufacturing decisions and the broader direction of the business. He has also been guiding the promoters alongside Kumar Sharat Chandra, who brings extensive experience from Indian Railways.
The link with Jagdamba Liquified Steels Limited
Jagdamba Liquefied Steels Ltd. was promoted by Mr. Yogesh Lohia and Mr. Lokesh Lohia among others. Mr. Yogesh Lohia is the father of Neetu Yoshi promoters, Subodh and Himanshu. JLSL appears to have defaulted on loans issued by Indian Bank. Indian bank had declared the JLSL account as NPA in 2022 and has filed a case against JLSL and its promoters and guarantors towards the recovery of an amount of INR 25Cr.
While Mr. Yogesh Lohia is not formally part of Neetu Yoshi in any capacity, it is clear from checks on the ground that he remains very actively involved in the business and his sons appear to draw heavily from his long experience with the Railways in running the business of Neetu Yoshi.
Therefore, investors must keep in mind that the existing promoters have a past track record of defaulting on bank loans for which they were taken to Court by banks.
Expansion into new railway segments:
Neetu Yoshi Ltd initially focused largely on components used in freight wagons but has gradually expanded its product portfolio toward railway infrastructures, components for tracks and passenger trains. Neetu Yoshi Ltd is now looking to move further up the value chain by developing products such as complete bogie assemblies, couplers, springs and turnout fittings.
Key Milestone in Neetu Yoshi Ltd. history
Details of Neetu Yoshi IPO and its further Warrants issue
IPO – A complete fresh issue of 77crs @ INR 75 per share, got listed at 40% premium on BSE SME exchange in July 2025.
Use of 77crs – ₹50.78 Cr capex for funding of new Haridwar facility & Balance 20crs is for General corporate purpose
Neetu Yoshi Ltd Preferential Warrant Issue
Following the IPO, Neetu Yoshi Ltd raised ₹27.48 crore through the preferential issue of 26.42 lakh convertible warrants at ₹104 per warrant in April 2026. Of the total warrants, 6.00 lakh (22.7%) were allotted to promoter Subodh Lohia, while 20.42 lakh (77.3%) went to non-promoter investors.
Use of funds – To fund working capital for the company’s new track component and turnout business. Raw material procurement for track turnouts involves buying finished rail sections (sourced from steelmakers like Jindal) at ₹65–70 per kg, compared to foundry scrap at ₹37–39 per kg as track assemblies require holding around 2 months of inventory prior to final assembly and dispatch to Indian Railways, the company raised this targeted capital to fund the expanded inventory cycle. This capital is expected to be fully deployed over next 1yr
Neetu Yoshi Ltd Management details
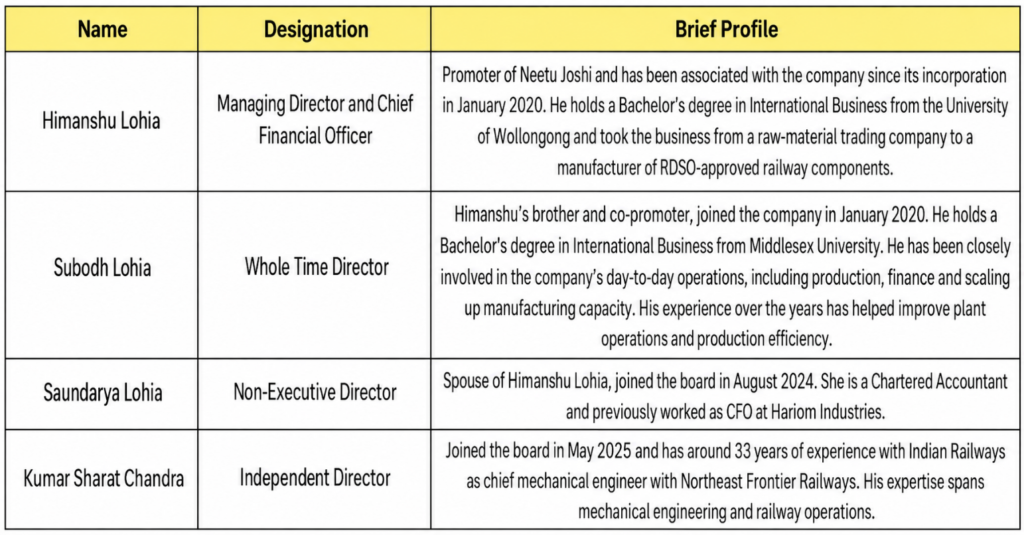
Himanshu Lohia is a second-generation entrepreneur and the public face of the company. He runs the business alongside his younger brother, Subodh Lohia. The company is named after his late mother, Neetu.
Neetu Yoshi Ltd – Industry Landscape
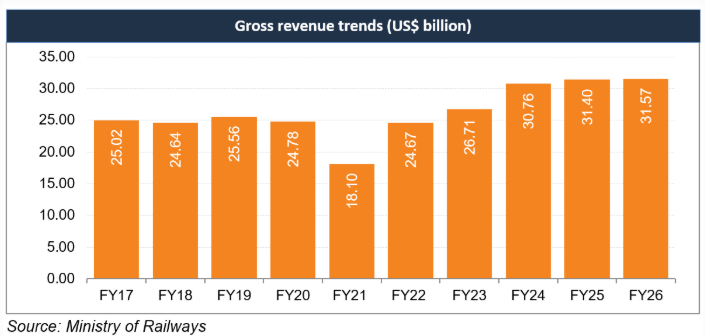
The India Railway Market is projected to expand from USD 32 billion in 2026 to USD 49 billion by 2031, at a CAGR of 7.20%. Indian Railways’ gross revenue stood at Rs. 2.79 trillion (US$ 31.57 billion) for FY26 due to freight-led earnings model and steady growth in passenger revenues. Freight activity is concentrated along mineral, industrial and port-linked corridors connecting eastern coal belts, central manufacturing clusters and western gateways.
The Indian government’s official goal under the National Rail Plan is to increase the modal share of freight traffic handled by railways from 27% to 45% by 2030 through expansion of dedicated freight corridors
Dedicated Freight Corridor – A Dedicated Freight Corridor (DFC) is a high-capacity, high-speed railway track system built exclusively for the movement of freight and goods trains, separate from regular passenger traffic.
Operational DFCs – India has commissioned its initial two major freight corridors spanning a combined 2,843 km:
- Eastern Dedicated Freight Corridor: Runs 1,337 km from Ludhiana (Punjab) to Sonnagar (Bihar).
- Western Dedicated Freight Corridor: Runs 1,506 kms from Dadri (Uttar Pradesh) to the Jawaharlal Nehru Port Trust (JNPT) near Mumbai.
Planned DFCs –
- East-West Corridor: Kolkata region to the Mumbai/Surat region (approx. 2,100–2,328 kms)
- East Coast Corridor: 1,115 kms from Kharagpur (West Bengal) to Vijayawada (Andhra Pradesh).
- North-South Sub-Corridor: 975 kms from Itarsi (Madhya Pradesh) to Vijayawada (Andhra Pradesh) via Nagpur
- The estimated cost for the above 3 planned corridors is around 1.5 Lakh crores
Indian Railway Equipment Market Industry
Indian Railway Equipment Market was valued at USD 12.31 Billion in 2023 and is anticipated to project robust growth in the forecast period with a CAGR of 3.61%. With a vast network of over 67000 km of tracks, Indian Railways plays a crucial role in the country’s transportation system. The government’s substantial investments in the railway sector are evident in ambitious projects like the Dedicated Freight Corridor and the High- Speed Rail Project, which are set to revolutionize transportation in India.
For FY27, the government has allocated ₹2.78 lakh Cr towards railway capital outlay and is spread across areas of the railway ecosystem, including ₹52,108 Cr for rolling stock, ₹36,721 Cr for new railway lines and ₹22,853 Cr for track renewal and structural maintenance.
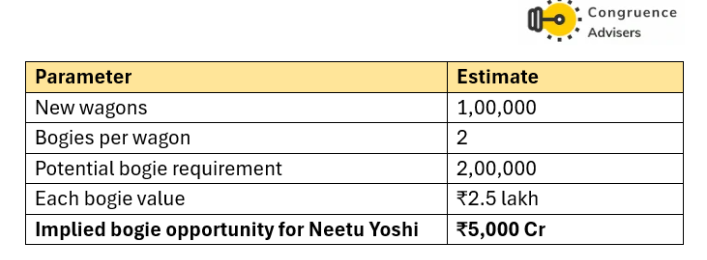
One of the clearest near-term opportunities is the planned procurement of around 1 lakh new freight wagons. The proposed tender is estimated at around ₹40,000 Cr over 3–4 years, implying an average wagon value of roughly ₹40 lakh.

The opportunity becomes more interesting at the component level. Each wagon requires two bogies, which means 1 lakh new wagons could translate into around 2 lakh bogies
Each bogie value of ₹2.5 lakh, this represents a potential bogie opportunity of approximately ₹5,000 Cr, over next 3-4yrrs.
Railway Components Entry Barrier
Railway component manufacturing has a high qualification barrier because several components are safety critical. RDSO (Research Designs and Standards Organisation) acts as the key technical and vendor-approval body for Indian Railways.
For safety-critical components, vendors have to go through a detailed qualification process involving factory audits, capability assessment, sample testing, field trials and performance monitoring. Foundries supplying critical castings require Class “A” foundry certification, to manufacture railway-grade castings to the required standards
Once a company has successfully completed these processes, the qualification becomes an important competitive advantage because customers are less likely to switch suppliers for safety-critical components without a comparable approved alternative.
Neetu Yoshi ltd sits between raw-material suppliers and the larger railway OEMs =
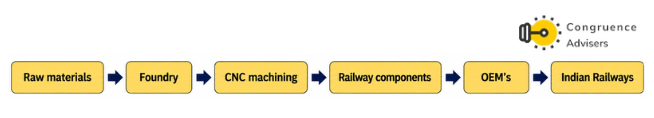
Neetu Yoshi ltd is primarily exposed to safety-critical components used in braking, suspension, coupling, bogie and other railway applications. Its Class-A RDSO certification and product approvals provide entry into an ecosystem where vendor qualification is an important competitive barrier.
Neetu Yoshi Ltd Business Details
Neetu Yoshi Ltd is building a broader manufacturing presence across the Indian railways ecosystem, leveraging the strong promoter connections with Indian Railways. First, we will start by understanding the Indian Railways ecosystem and then delve deeper into the business verticals and product portfolio of Neetu Yoshi Ltd.
Where does Neetu Yoshi Ltd fit in the Indian Railways Ecosystem?
The Ecosystem is broadly divided into
1. Railway Administration
Indian Railways is divided into 17 zones, which are responsible for the day-to-day operation, administration and maintenance of the railway network. These zones ultimately represent the end-market that drives demand for railway infrastructure and equipment.
2. Railway Production Units
Indian Railways also operates dedicated manufacturing units for rolling stock. Key facilities include ICF (Chennai), RCF (Kapurthala) and MCF (Raebareli) for coaches, while CLW (Chittaranjan), BLW (Varanasi) and PLW (Patiala) are involved in locomotive manufacturing.
3. Private Rolling-Stock Manufacturers
Private players such as Jupiter Wagons, Titagarh and Texmaco manufacture wagons, coaches and other railway equipment. These companies typically source several specialised components from external vendors.
4. Railway Component Manufacturers
This is the segment where Neetu Yoshi primarily operates. Component manufacturers supply specialised and safety-critical parts that go into wagons, coaches and locomotives. These include bogie components, brake components, suspension parts, coupling components and other precision-engineered parts.
5. Track Infrastructure
A separate part of the ecosystem is the railway track infrastructure segment. This includes rails, turnouts, crossings and track fittings. Indian Railways is the key customer, while specialised private vendors manufacture and supply various components used in track construction and maintenance, Neetu Yoshi recently started operating in this.
6. Bridges & Structures
The railway network also requires a wide range of bridges, structural components and related infrastructure. These projects are executed by Indian Railways and EPC/infrastructure companies, with specialised vendors supplying individual components, Neetu Yoshi recently started operating in this.
Neetu Yoshi Ltd primarily sits in the component manufacturing layer, while its newer track turnout and structures business gives it exposure to the track & bridge infrastructure segment as well
What products does Neetu Yoshi Ltd manufacture?
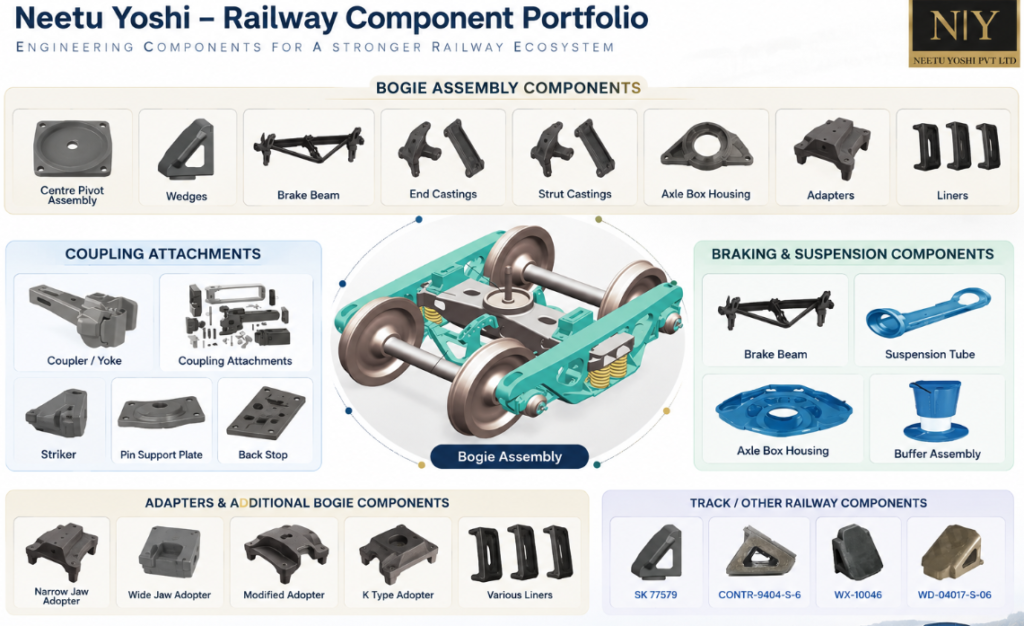
Neetu Yoshi’s Product segments :
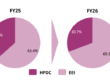
Freight Wagon Components (Core Business) – Neetu Yoshi Ltd is RDSO Class ‘A’ approval for more than 25 critical wagon safety components and supplies components to private wagon manufacturers such as Jupiter Wagons and Titagarh
Passenger Coach Components – Neetu Yoshi Ltd has started moving beyond freight wagons into passenger-coach applications and has received vendor approval from ICF Chennai for Buffer Assemblies and has also received CCA approval from RCF Kapurthala for FIAT bogie brake support
Locomotive Components – Components such as axle box housings and suspension tubes
Track & Bridge Infrastructure – Instead of supplying only individual Track Welded System (TWS) fittings, it is now working towards supplying complete track turnout assemblies.
This segment also requires more working capital because the company purchases finished rail sections at around ₹65–70/kg from players like Jindal steel, compared with much lower-cost foundry scrap used in its traditional business at ₹37-39/kg. The raw material remains in inventory for around two months before final assembly and dispatch. To support this expansion, Neetu Yoshi Ltd raised ₹27.48 Cr through convertible warrants, with the funds being used primarily for working capital in the track and turnout business.
Neetu Yoshi Customer Details
Neetu Yoshi’s customers are major private-sector original equipment manufacturers (OEMs) such as Jupiter Wagons, Titagarh Rail Systems, Texmaco Rail & Engineering, Jindal Rail Infrastructure, and Hindustan Engineering & Industries
Neetu Yoshi Ltd also supplies its products to government railway departmental production units such as the Integral Coach Factory (ICF), Rail Coach Factory (RCF), and Modern Coach Factory (MCF), alongside zonal repair workshop
Neetu Yoshi Ltd Manufacturing facilities
Neetu Yoshi Ltd currently operates two manufacturing facilities in Uttarakhand –
- Fakkarhedi, Bhagwanpur facility
- New Haridwar Plant (for bogies & couplers)
Fakkarhedi, Bhagwanpur facility (Core facility)
- Installed capacity of 8,087 MTP
- This plant manufactures bogie components up to 100kgs
- At full utilization, this plant can do revenues of 110crs
- Currently, operating at 90% utilization
Adjacent to the same core facility – Bhagwanpur
- Neetu Yoshi Ltd has set up a 3,000 sq. metres dedicated shed for track products in FY26
- The key requirement for this business is working capital. Unlike standard foundry castings that are made from cheap railway scrap (procured at ₹37–39/kg), complete track turnouts require purchasing finished rail sections directly from primary steelmakers (such as Jindal) at ₹65–70 per kg and holding 2 months of raw material inventory, hence led them to do a preferential issue of 27crs.
- The track business contributed around 20 Crs in FY26, mainly from TWS fittings and wear plates.
- Commercial dispatches of complete track turnout assemblies and direct bidding on Indian Railways track tenders scale up across FY27
- From this 3,000 sq. mts shed, management is expecting to 60-70crs of revenue in next 1.5 to 2yrs
New Haridwar Plant (for bogies weighing beyond 100kgs & couplers)
- Installed capacity of 13,200 MTPA
- Became operational in August 2026
- Incurred a capex of 50crs out of IPO proceeds
- Originally planned 50crs capex to be incurred in Kanpur, Uttar Pradesh, then project was strategically relocated to Haridwar, Uttarakhand because RDSO gave written confirmation that inspections could instead be conducted from the Haridwar zone
- In this plant, Neetu Yoshi Ltd plans to manufacture Side beam of 400kgs & Bolster of 800kgs and these components are used in bogies and eventually, the company intends to do assembly of 500 bogies on monthly basis
- At full utilization, this plant can generate a revenue of 240crs resulting in asset turns of 4.8x
- Ramp up of this facility –
- Neetu Yoshi Ltd plans to utilize 50 – 60% of its capacity in FY27, leading to a revenue of 110crs
- By FY28, the company plans to full utilize its capacity by doing a revenue of 240crs
Strategically located plants
Core facility Bhagwanpur is just 72.6 kilometres from the Jagadhri Railway Workshop (Northern Railways), allowing low-cost metal scrap that Neetu Yoshi uses it as raw material for their products
Raw Material Cost Savings Compared to its Peers – Instead of buying expensive commercial pig iron or standard scrap from open markets, Neetu Yoshi buys around 700 MT per month of railway scrap directly from nearby workshops (like Jagadhri and Charbagh) via official auctions. This leads to savings of ₹4 per kg compared to its peers
Sourcing raw scrap at INR 35 to 39 per kg and then transforming it into , RDSO-approved safety railway components yield significant price spreads
- Wagon parts: Sold at ₹110 per kg
- Track fittings: Sold at ₹140–150 per kg
- Passenger coach parts: Sold at ₹220–250 per kg
As foundries are intensive, Uttarakhand offers some of the lowest industrial electricity tariffs in India compared to major competitors foundries located in Kolkata or Uttar Pradesh
Located relatively close to silica sand sources along the Ganges (e.g., Allahabad), reducing bulk sand transportation costs
Neetu Yoshi Ltd upcoming capex (Near its core facility Bhagwanpur)
- Neetu Yoshi Ltd acquired a land of 2,500 sq. mts to build a hot and cold coil spring plant, whose springs are used in bogies and has planned a capex of 12 to 15crs in FY27
- Revenue is expected to be generated in the same FY27 with a potential to do revenues of 35crs
Combining all the facilities including upcoming small capex of 12crs to 15crs for spring plant,
- Neetu Yoshi Ltd can pull off revenues of 440crs of revenue, its FY26 revenues stand at 98crs whereas their revenue potential is 4x from the current levels
Neetu Yoshi Ltd Corporate governance details
Board Composition – The Board comprises 6 members of whom 3 are promoter family members and only 2 are independent directors. Thus, Board independence is compromised.
Related Party transactions – There are no material RPT transactions that are worth flagging
KMP Remuneration – KMP remuneration is 10% of FY26 PAT which is acceptable
Contingent Liability – Neetu Yoshi Ltd has no contingent liabilities that are disclosed in the Annual Report of FY26.
A detailed corporate governance check would entail looking at these additional factors, if and when we get to writing a detailed initiation note on this business
- Intangibles involved in the business, do they form a big part of the balance sheet?
- Unit economics – do they fit into the normal range for a business of this nature?
- Is accounting complicated or simple? consistent or changes every few years?
- Consistency in disclosing FX losses/gains and MTM impact?
- Consistency in tax outgo in the cash flow statement and the P&L?
- Is the promoter family actively investing outside of the business- real estate, VC Funds?
- What other organizations are the promoters and directors associated with? Any history of defaults or frauds there?
- Any history of over the top speak by promoters/management in the media?
- Analysis of audit committee notes
- History of change/retention of statutory auditors & auditor remuneration trend
- Insights from credit rating reports
- Pending litigation against company & promoters?
It has been our endeavour over the years to enhance the scope and details of the corporate governance checks we conduct. However, the entire scope of this analysis would be an overkill at this stage of business analysis. This will be appropriate for a deep dive if and when a business is considered for inclusion in the portfolio.
Neetu Yoshi Ltd Financial Performance
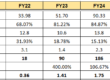
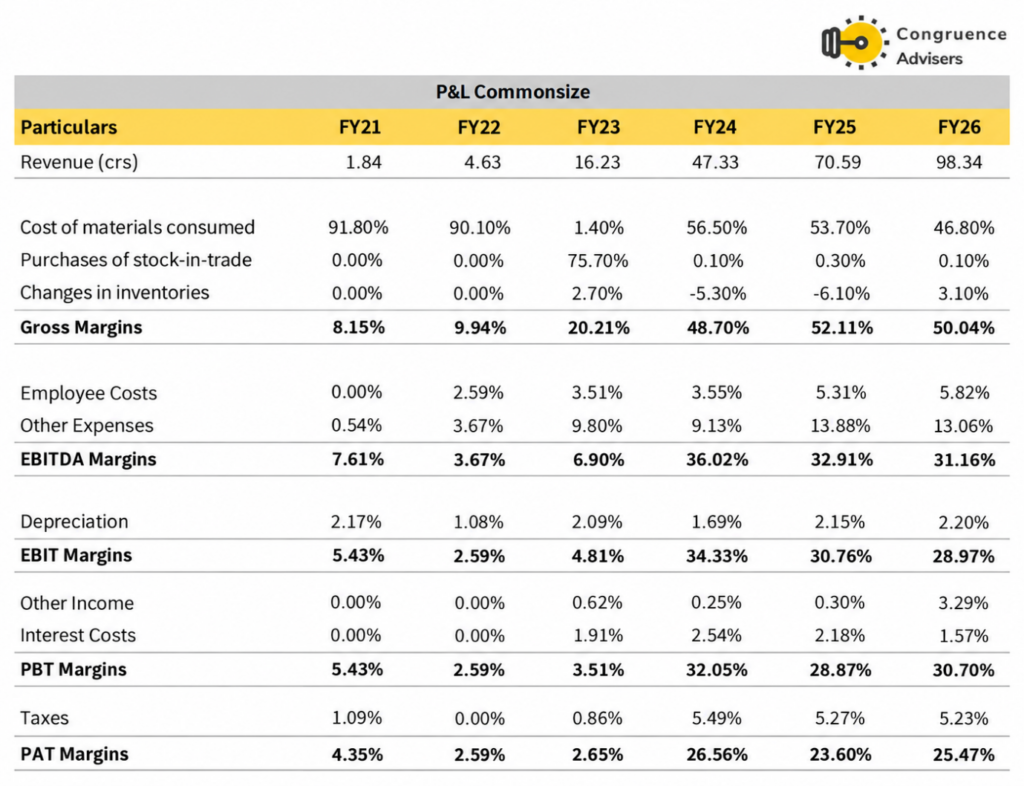
Neetu Yoshi Ltd has scaled well from ₹1.84 Cr revenue in FY21 to almost 100 Cr in FY26, this growth has been driven by rapid shift in their business from being a railway scrap trader to becoming a manufacturer of railway safety components. Neetu Yoshi has no exports, currently its entire focus is on capitalizing the Indian railway components opportunity.
Neetu Yoshi Ltd’s latest capex of ~INR 50 Cr for their new Haridwar plant would hardly affect its P&L through depreciation as the company’s historical depreciation rate is around 8.5% of Gross block.
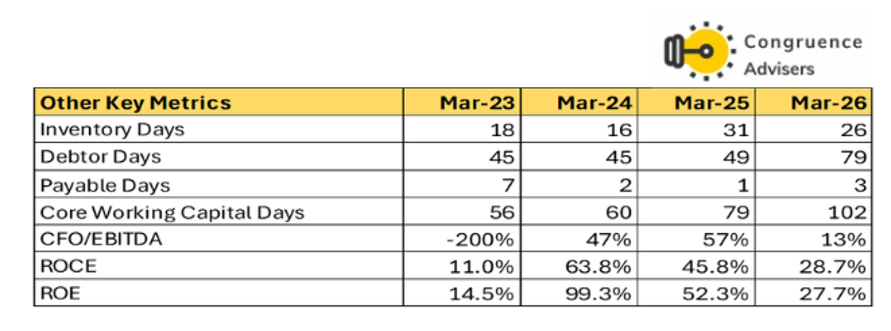
Risk lies in their working capital days, their working capital days went from 73 days in FY24 to 126 days, one has to be aware of the recent new products particularly railway tracks, whose customer is Indian Railways and the company has raised warrants for the same, however it is important to track their future working capital days more deeper as they are increasing their revenue contribution from these tracks products going ahead
Neetu Yoshi Ltd Comparative Analysis
To understand Neetu Yoshi Ltd investment potential, we have conducted a comprehensive analysis. This analysis includes comparing Neetu Yoshi Ltd to its competitors (peer comparison) on various fundamental parameters and Neetu Yoshi Ltd share performance relative to relevant benchmark and sector indices.
Note: Comparable peers to Neetu Yoshi Ltd are not available in the listed universe. Hence, we benchmarked Neetu Yoshi Ltd against its closest peers such as Frontier steel, Anjaaney Rails and Atul Engineering who are unlisted companies.
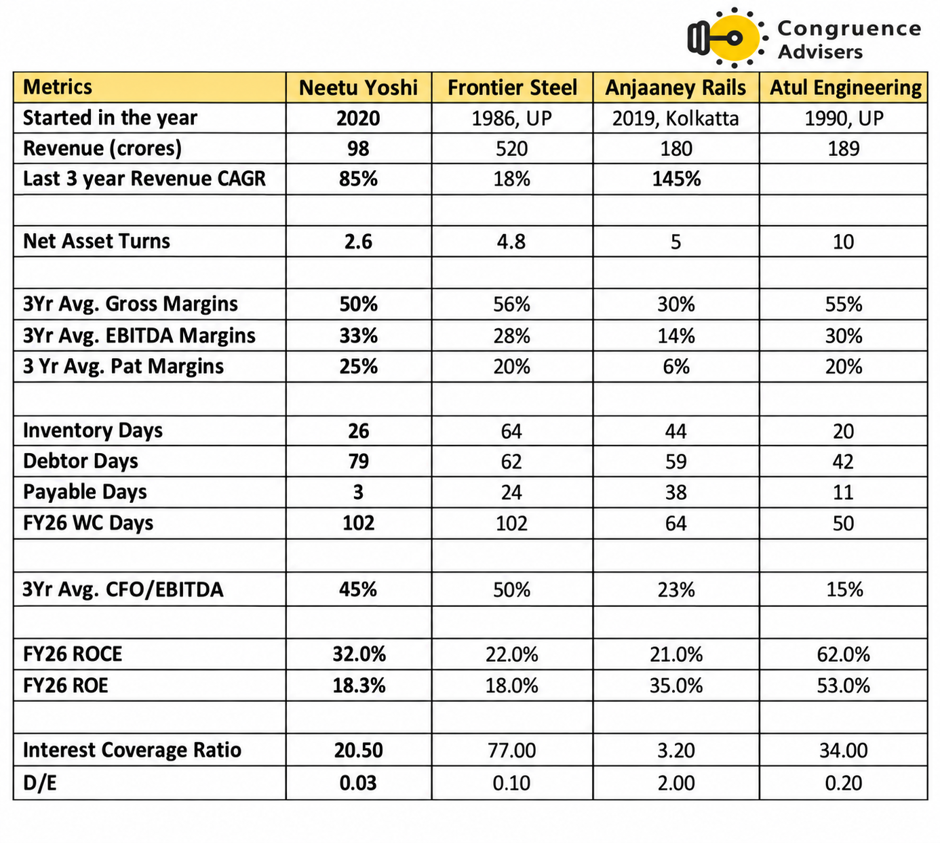
Neetu Yoshi Ltd clearly beats all of its peers in EBITDA margins significantly even though their peers have been in the railway components business for decades. The main reason as to why Neetu Yoshi Ltd beats them is due to their machinery equipment such as automatic high-pressure moulding equipment which is a modern moulding equipment compared to its peers who use manual hand moulding technique.
Rather than competing in lower-margin, commoditized fabrication, Neetu Yoshi Ltd deliberately targets safety-critical precision parts with high technical barriers and limited competition
Neetu Yoshi Ltd Index Comparison
Neetu Yoshi Ltd share performance vs S&P BSE Small Cap Index, as the index benchmark comparison is a fundamental tool for understanding the investment potential and making informed decisions in the context of the broader market
TABLE – T2
Why You Should Consider Investing in Neetu Yoshi Ltd?
Neetu Yoshi ltd offers some compelling reasons to track closely and to consider investing in India railway manufacturing components player
Hungry for growth and Phenomenol journey – What Neetu Yoshi ltd has done in the last 4yrs is phenomenal when compared to its peers who has been in this business since 40yrs, Neetu Yoshi ltd has been able to pull off 100crs of revenues within 6yrs since its incorporation. The management is guiding for 50% growth in FY27 and one more 50% growth in FY28 as clearly visible from the capex they carried out in the last 2yrs.
Industry leading margins – Neetu Yoshi ltd has been able to maintain their margins by making critical safety railway bogie components and has plans to do complete bogie assembly, management maintains a strict hurdle rate, focusing exclusively on high-margin, safety-critical precision parts.
Structural Cost Advantages in Power & Raw Materials – Operating in Uttarakhand gives access to some of the lowest industrial electricity tariffs in India, significantly reducing melting costs for its furnaces. Sourcing high-grade railway scrap directly from nearby railway workshops (such as Jagadhri which is 72 km away) at 35–39/kg gives an estimated 4/kg cost savings over market rates
High-Value Forward Integration into Bogies & other parts of couplers – Neetu Yoshi ltd is expanding beyond lightweight parts (<100 kg) into complete heavy assemblies weighing up to 800 kgs at its new Haridwar plant. Assembling up to 500 complete bogies per month alongside couplers significantly increases the revenue realization per bogie unit.
Margin Protection via Price Variation Clauses – Contracts with Indian Railways and with private OEMs incorporates contractual price variation clause thereby insulating the Neetu Yoshi ltd’s margins
Product Diversification – Neetu Yoshi ltd expanded beyond freight wagon parts into higher-margin segments, including passenger coach components (ICF buffer assemblies, main bogie components such as bolster), locomotive parts (axle box housings), track turnouts, and upcoming hot/cold coil springs
What are the Risks of Investing in Neetu Yoshi Ltd?
Investors need to keep the following risks in mind if they choose to invest into this business. Risks needs to be weighed in combination with the advantages listed above to arrive at a decision that is optimal for your portfolio construct
Past sins of the promoter cannot be ignored – The Jagdamda Liquified Steels Ltd. loan default and subsequent debt recovery tribunal case against the company should not be ignored as it proves that in the past this promoter group has defaulted on bank loans.
Execution risk – Revenue guidance of 50% growth in FY 27 and again in FY28, is getting priced in the recent rally, any material deviation from their ability to execute the same could be bad.
Slow down of capex in the Railway industry – With the new announcement of 40,000 Cr worth of wagons could lead to good days for the railway components makers such as Neetu Yoshi Ltd, however if there is any slow down in railway capex in upcoming years could create lumpiness in their revenues and possibly in their margins as well, as Neetu Yoshi Ltd is currently restricted to only to railway components.
High Working Capital Requirement for New Product Segments – Neetu Yoshi Ltd’s new products like complete track turnouts requires holding 2 months of high-cost raw material inventory prior to assembly and dispatch which forces them to rely on external equity/warrants funding to support working capital growth, though Neetu Yoshi Ltd recently raised 27crs through warrants.
Concentration Risk – Indian Railways and its ecosystem account for most revenues, any changes in tendering, procurement policy or offtake could affect its order book. Revenue from their three customers have contributed 52% of the FY26 revenues with Customer A generating revenues of 28crs, Customer B -12crs and Customer C – 10crs.
Liquidity risk – Neetu Yoshi Ltd is an SME stock with relatively low trading volumes and high price volatility. Limited market depth can make it difficult to exit positions particularly during periods of market stress.
Neetu Yoshi Ltd Outlook
Neetu Yoshi Ltd has been guiding for a phase of high growth over the next few years on the back of good order visibility and product portfolio expansion.
FY27
- Guided for 210–220 Cr revenue in FY27.
- New Haridwar plant is expected to operate at around 50–60% utilisation and contribute roughly ₹100–110cr, while the existing Bhagwanpur facility is expected to generate around 110–130crs
- Management is targeting a 25% PAT margin
FY28 –
- Targeting revenues of 340–350 Cr in FY28
- Haridwar could contribute around 200–240 Cr at peak capacity, while the track products business is expected to generate 60–70 Cr.
FY29 –
- By FY29, Neetu Yoshi Ltd plans to move further up the value chain by transitioning from a component and sub-assembly supplier to a complete wagon manufacturer
- Targeting an initial production of around 200 wagons annually
FY30 & beyond –
Over the longer term, Neetu Yoshi Ltd is exploring opportunities in defence, mining and thermal power equipment, while also planning for exports of railway components.
Neetu Yoshi Ltd Technical Analysis
We consider technical analysis to be a useful input in taking medium-term investment decisions. Many a time price action tends to lead to fundamental developments; this is too important an aspect to be ignored by retail investors who do not have access to management outside of common forums like investor calls & AGM.
At Congruence Advisers we like to consider both the long-term weekly chart and the daily chart to arrive at a view on price action. Combined with our understanding of fundamentals, we usually end up being better placed to be able to judge both the business cycle and the stock cycle. Playing the stock cycle right is extremely important for investors looking to extract significant alpha over the medium term.
Neetu Yoshi Ltd Price Charts
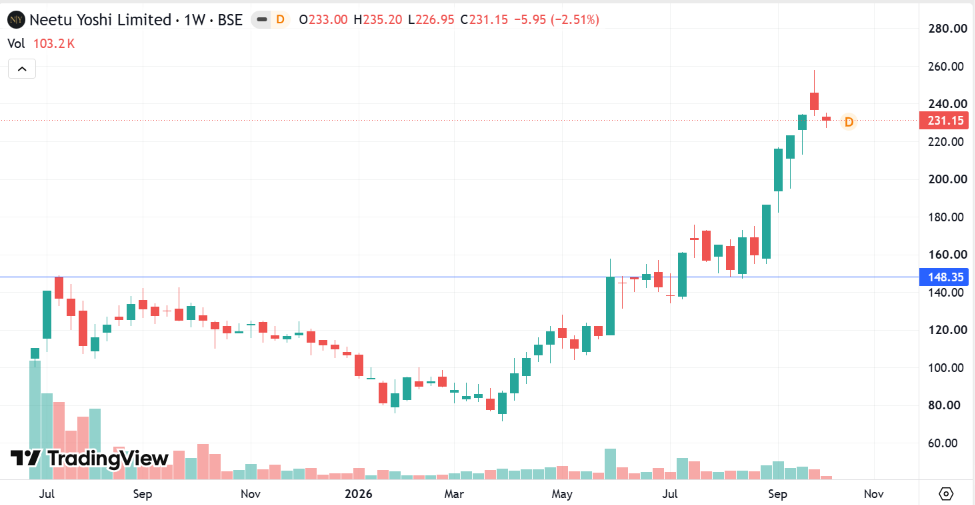
Neetu Yoshi was listed in June 2025, so the entire stock price history is captured in the weekly chart above. After a strong listing, the stock peaked in July 2025 around INR 150 and then spent the next 8 months in a correction phase, like most of the SME and microcap market. The stock bottomed in end March with the rest of the market and then reclaimed its IPO high levels of ~150 in June backed by strong H2 FY26 earnings declared at the end of May.
The stock spent the next 3 months consolidating in and around the IPO highs, before decisively moving upward after the fund raise via warrants closed in late August 2026. The stock had a stellar September and moved up almost 60% in the month. Since then the stock has been in a much needed consolidation phase for the last week or so.
One would expect the consolidation to continue for a while as H1 FY27 results will be much weaker than H2 FY27 results because only 1 month of the new plant commissioning will get captured in the first half. A better than expected result or very bullish concall commentary, can take the stock to new highs.
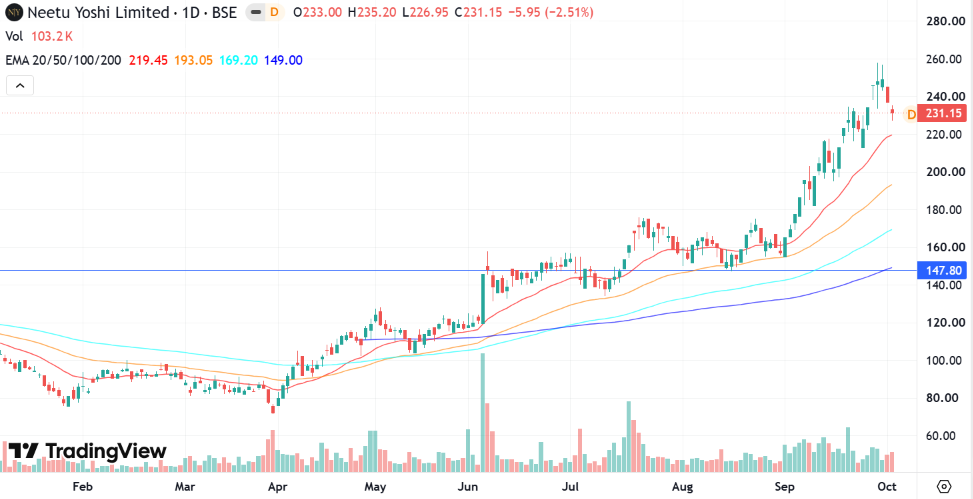
The daily chart captures the price movements in the calendar year 2026. The golden cross (50DMA overtaking 200DMA) happened in early June right after the strong H2 FY26 results were declared. Since the high volume move on 4th June 2026, the stock has respected its 50 DMA line and never cracked below it. Since the late August retest of the support line at 148 and the successful warrants issuance the stock has run up violently staying above its 20DMA consistently. The recent consolidation after the run up should very likely respect the 50DMA line unless there are some unexpected negative developments or a poor H1 FY27 result. A touch of the 50DMA line may be a buying/topping-up opportunity if the story is tracking expectations.
Neetu Yoshi Ltd Latest Result, News and Updates
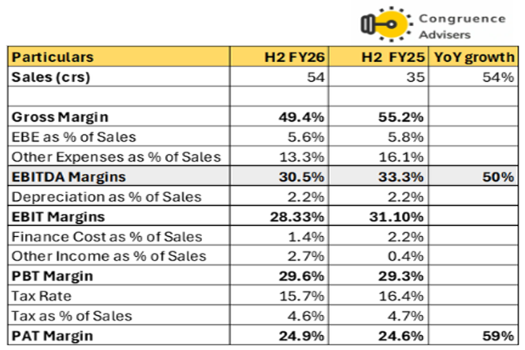
Neetu Yoshi Ltd Half-Yearly Results
Total Order Book: 140 crores as of FY26
- Coach Components Segment: Accounts for 40% of the order book
- Wagon & Bogie Segment: Accounts for 30%
- Track Infrastructure Segment: 20% to 30% of the order book
As on 19-09-2026, Neetu Yoshi Ltd secured RDSO Prototype Approval for Friction Wedge, Extending its reach to High-Speed “Raftar” Bogies
- Friction Wedge is a critical safety component used within the bogie suspension system, fitted between the bolster and the side frame to control the damping force that governs a wagon’s ride behaviour
- With this approval, Neetu Yoshi Ltd is now eligible to commence supply of the item to Indian Railways and its associated agencies.
Final Thoughts on Neetu Yoshi Ltd
Neetu Yoshi has done very well to transition from a railway scrap trader in 2020 to an RDSO certified components supplier for wagons, tracks and passenger coaches in 2026. The vast experience of the promoters’ father with the railways in his previous company and his connections in Railways, has no doubt helped them make this rapid progress.
With the new Haridwar wagon plant recently commercialised, the company appears to be on a very strong revenue growth trajectory. With the claimed price variation clauses in place, margins should be broadly defensible. At present the company works on ~100-130 days of net working capital. This will increase as % of direct revenue from Railways increases. It’s commendable that the company has kept its balance sheet completely debt free while growing this fast. For a small railway components business to consistently generate positive cash flow every year is not a small feat. Working capital discipline and cash flow stress are the two things investors should watch out for here as the steep growth pans out.
A perennial risk in Govt facing businesses is any sudden cuts in budgets which affect demand visibility. While that’s certainly possible here, it does appear that the Indian Railways wants to increase its goods rolling stock and tracks significantly to capture a larger share of India domestic logistics spend. While the recent move in price has squeezed some of the near term juice out of the opportunity, if the company can execute their planned FY28 growth, there still appears to be a decent upside left in the story.
Disclaimer – This note is part of a business research & analysis series on small companies, there is no BUY/SELL recommendation or target price issued as part of this to a general audience. There is no assurance that this stock makes for a good investment, there is no guarantee that this stock will continue/be included in the coverage universe of Congruence Advisers. The note contains some forward-looking statements and insights drawn from the historical results, annual reports and investor presentations; they are to be viewed only within this context and not as a prediction of future performance of the business or the stock covered.
While due care has been taken to ensure that the information here is as accurate as possible, Congruence Advisers disclaims any liability in case of any unintentional inaccuracies.
The content does not constitute investment advice.